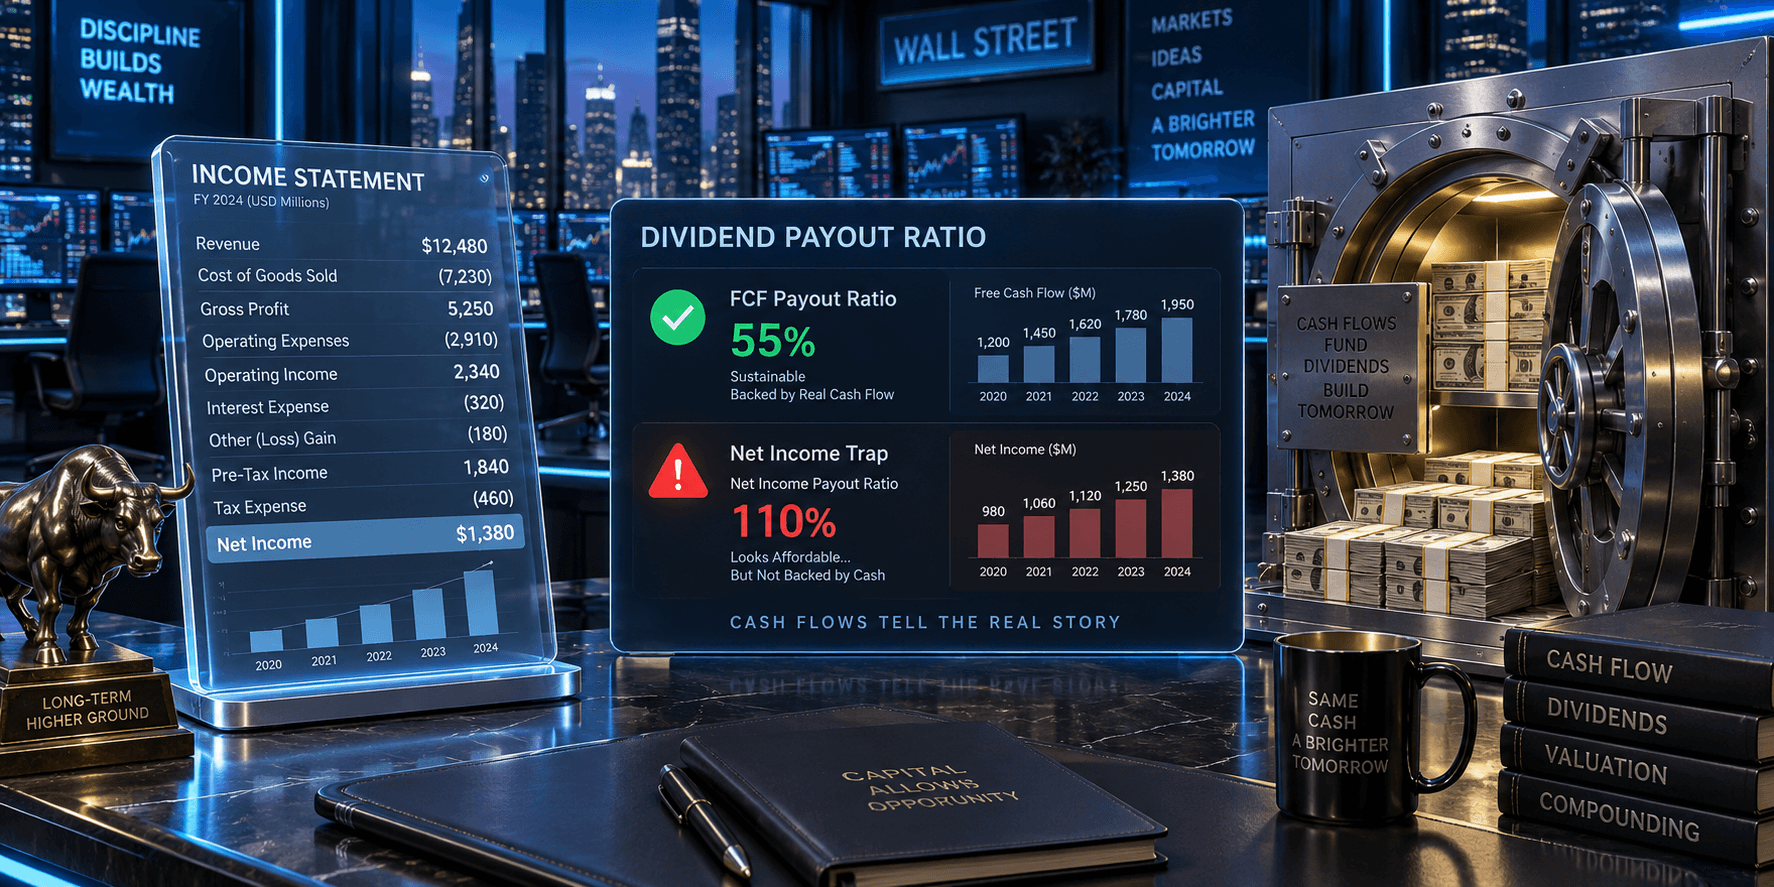
A dividend payout ratio measures how much of a company’s earnings or cash generation is being returned to shareholders as dividends. The arithmetic is straightforward, but there is no single percentage that can determine dividend safety across every company or industry.
The traditional earnings payout ratio and the free cash flow payout ratio answer different questions. The first compares dividends with accounting earnings. The second compares dividends with a cash-flow measure after capital spending. Used together, they can help investors identify cases where reported earnings and actual cash coverage are telling different stories.
Earnings payout ratio = Common dividends ÷ Net income available to common shareholders × 100
FCF payout ratio = Cash dividends paid ÷ Free cash flow × 100
FCF dividend coverage = Free cash flow ÷ Cash dividends paid
When calculating either ratio, the numerator and denominator should cover the same reporting period and use compatible definitions. For common stocks, investors may also encounter the earnings payout ratio expressed as dividends per share divided by earnings per share.
What a Dividend Payout Ratio Actually Measures
The traditional payout ratio uses GAAP net income as its earnings base. This is useful because net income captures the company’s accounting profitability after operating expenses, interest, taxes and other recognized gains or losses.
However, GAAP earnings are prepared using accrual accounting. Revenue can be recognized before the related cash is collected, while depreciation, amortization, impairments and other non-cash items can materially affect reported earnings. That does not make net income unreliable. It means the payout ratio needs to be interpreted in the context of the financial statements.
A free cash flow payout ratio approaches dividend coverage from a different direction. One commonly used form of free cash flow starts with operating cash flow and subtracts capital expenditures.
The SEC’s guidance on non-GAAP financial measures notes that free cash flow does not have a uniform definition. The SEC also cautions against presenting FCF as though it represents all residual cash available for discretionary spending because mandatory debt service and other non-discretionary cash requirements may remain outside the calculation.
That limitation is important for dividend analysis. FCF can provide a useful cash-based cross-check, but the ratio should not replace a review of the full cash flow statement, debt obligations and liquidity position.
Net Income Payout Ratio vs. FCF Payout Ratio
| Metric | Common Calculation | What It Helps Measure | Main Limitation |
|---|---|---|---|
| Earnings payout ratio | Common dividends ÷ earnings available to common shareholders | How much reported profit is being distributed | Non-cash and one-time accounting items can affect net income |
| FCF payout ratio | Cash dividends ÷ consistently defined FCF | How much measured free cash flow is used for dividends | FCF definitions vary and may exclude other required cash uses |
| FCF dividend coverage | FCF ÷ cash dividends | How many times measured FCF covers dividend payments | Short reporting periods can be distorted by cash-flow timing |
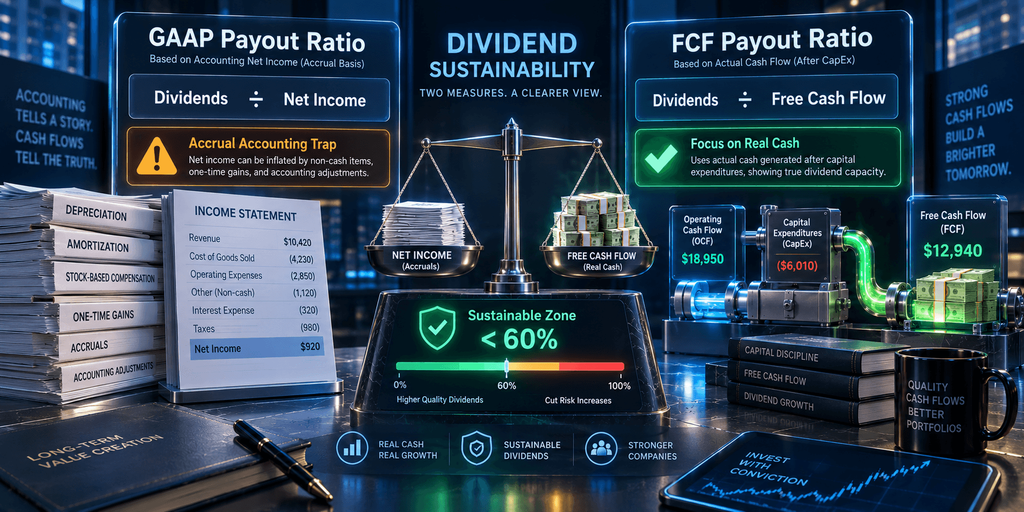
The ratios become more useful when investors compare them over several reporting periods. A temporary inventory build, tax payment, receivables swing or capital-spending cycle can move free cash flow sharply even when the long-term economics of the business have not changed.
Why There Is No Universal 60% Dividend Safety Rule
A lower payout ratio generally leaves more financial room for reinvestment, debt reduction and unexpected cash needs. But that does not mean every company below 60% has a secure dividend or every company above 80% is approaching a dividend cut.
Business models differ too much for a single threshold to work across the entire market. An asset-light company with stable recurring cash flow may be able to operate with a higher payout ratio than a cyclical manufacturer facing large capital expenditures. A utility may generate predictable operating cash flow while also carrying significant infrastructure spending and debt. A pharmaceutical company can produce substantial cash while simultaneously funding acquisitions, research programs and contingent payments.
Instead of treating one percentage as a pass-or-fail test, investors can ask several questions together:
- Has free cash flow covered dividend payments across multiple reporting periods?
- Is the payout ratio rising because dividends are growing faster than earnings or cash generation?
- Did temporary working-capital changes distort the current period?
- Is unusually high capital spending related to expansion, maintenance needs or business deterioration?
- Are debt maturities, acquisitions or other major cash commitments competing with the dividend?
- Does the company maintain adequate liquidity after those obligations?
The direction and consistency of these measures usually provide more information than whether the current payout ratio sits above or below one fixed percentage.
AbbVie Shows Why a High FCF Payout Ratio Needs Context
AbbVie provides a current example. According to the company’s Form 10-Q for the six months ended June 30, 2026, operating cash flow totaled $7.265 billion and acquisitions of property and equipment totaled $587 million.
Using the simple operating-cash-flow-minus-capital-expenditures approach gives approximately $6.678 billion of first-half free cash flow.
$7.265B operating cash flow – $0.587B property and equipment purchases = $6.678B simple FCF
$6.156B cash dividends ÷ $6.678B simple FCF ≈ 92.2% FCF payout ratio
$6.678B simple FCF ÷ $6.156B cash dividends ≈ 1.08× FCF dividend coverage
AbbVie paid $6.156 billion of cash dividends during the same six-month period. On this simple FCF definition, the resulting payout ratio was approximately 92.2%, while FCF dividend coverage was about 1.08 times.
Viewed in isolation, a 92.2% payout ratio may appear tight. But it covers only six months. Operating cash flow can move with working-capital timing and tax payments, while acquisitions, debt service, share repurchases and other cash requirements also compete for capital outside a simple FCF-versus-dividend calculation.
The ratio is therefore a reason to examine the broader cash-flow picture, not an automatic dividend-cut signal. Our AbbVie Q2 2026 earnings and cash flow analysis looks at that coverage alongside the company’s post-Humira revenue transition and other capital demands.
For readers who want to review the underlying FCF calculation in more detail, the Smart Asset Desk free cash flow guide explains how operating cash flow and capital expenditures fit together.
A Practical Dividend Coverage Audit
A dividend payout ratio works best as part of a short financial-statement review rather than as a stand-alone screen.
- Identify the dividend amount for the period. For a historical cash-coverage analysis, the cash flow statement shows how much cash was actually distributed during that reporting period.
- Compare dividends with earnings. Check whether impairment charges, asset-sale gains, restructuring expenses or other unusual items materially affected net income.
- Cross-check free cash flow. Review operating cash flow and capital expenditures using the same reporting period and a clearly defined FCF calculation.
- Read the rest of the cash flow statement. Debt repayment, acquisitions, share repurchases and other financing or investing requirements can matter even when simple FCF covers the dividend.
- Compare several periods. Recurring deterioration in coverage usually deserves more attention than one unusually weak quarter or half-year.
Sector Differences Can Change the Best Payout Metric
The traditional net income payout ratio is not equally informative across every industry. Real Estate Investment Trusts are a common example because depreciation of real estate can materially reduce GAAP net income even when property operations remain stable.
Nareit’s definition of Funds From Operations starts with GAAP net income and makes adjustments that include real-estate depreciation and amortization, certain gains and losses from property sales, and specified impairment-related items. FFO is therefore widely used as a supplemental operating measure for equity REITs.
Analysts and REITs may also report Adjusted Funds From Operations. However, Nareit notes that AFFO has no standardized definition. Investors should therefore review how each company calculates AFFO before comparing payout ratios between REITs.
The broader principle extends beyond real estate: the earnings or cash-flow denominator should reflect the economics of the business being analyzed, and its definition should remain consistent when comparing periods or companies.
What a High Payout Ratio Does and Does Not Mean
A rising payout ratio can indicate that dividend growth is outpacing earnings or cash flow. That deserves attention because the company may have less room to absorb a downturn or fund other priorities.
But a payout ratio above 100% does not automatically mean a dividend reduction is imminent. Net income can be temporarily depressed by a non-cash impairment or another unusual accounting item. Free cash flow can also swing because of working capital or investment timing.
The opposite is also true. A low payout ratio does not guarantee a durable dividend. A company can report apparently comfortable coverage while carrying substantial debt, facing deterioration in its core business or preparing for a large capital-spending cycle.
Dividend sustainability is therefore a capital-allocation question as much as a ratio question. Dividend payments compete with reinvestment, debt service, acquisitions, share repurchases and liquidity requirements.
Frequently Asked Questions
Which dividend payout ratio is more useful: net income or free cash flow?
They answer different questions, so reviewing both is usually more informative. The earnings payout ratio compares dividends with accounting profit, while the FCF payout ratio compares dividends with a cash-flow measure after capital expenditures. A large difference between the two ratios is a reason to investigate the financial statements rather than automatically choosing one as the correct measure.
Does an FCF payout ratio above 100% mean a dividend cut is coming?
No. It means dividend payments exceeded the measured free cash flow for that particular period and under that FCF definition. Investors should determine whether the shortfall came from temporary working-capital movements, unusually high capital expenditures or a persistent decline in operating cash generation. Repeated shortfalls combined with weak liquidity or heavy debt obligations generally warrant more scrutiny than a single period above 100%.
Should REIT investors use the standard net income payout ratio?
It can still provide information, but it may be incomplete because real estate depreciation can materially affect GAAP net income. REIT investors commonly supplement net income with FFO and, where appropriate, company-specific AFFO measures. Because AFFO is not standardized, investors should check each company’s definition before making comparisons.
Investment Disclaimer
This article is for informational and educational purposes only and does not constitute a recommendation to buy or sell any security. Financial data and company conditions can change after the periods discussed. Investors are responsible for their own investment decisions and outcomes.