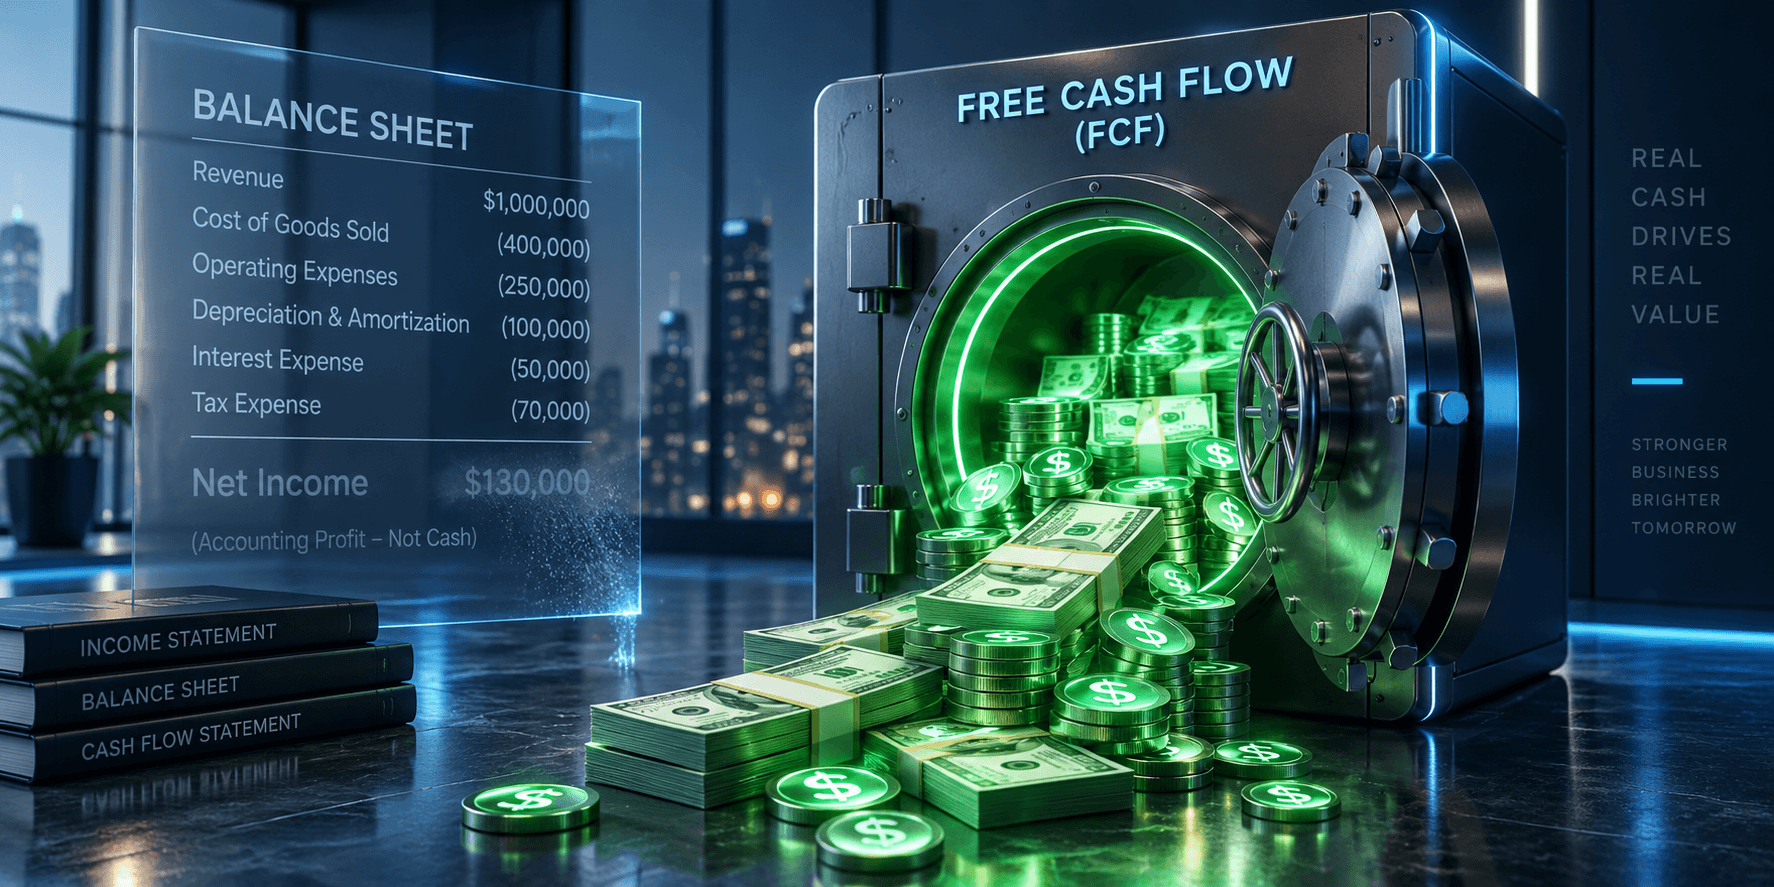
Free Cash Flow vs. Net Income: Why the Numbers Diverge
A comprehensive Free Cash Flow Guide starts with a simple idea: free cash flow measures cash a company generates after accounting for capital expenditures under the definition being used. Reported net income remains an important measure of profitability, but accrual accounting means earnings and cash generation can differ because of items such as receivables, non-cash expenses, and the timing of revenue and expenses.
Many equity investors begin with price-to-earnings multiples and quarterly GAAP net income when evaluating prospective holdings. Those measures can be useful, but they do not provide a complete picture of cash generation. Depreciation assumptions, inventory accounting, working-capital movements, and other accounting items can cause reported earnings and cash flow to move differently. Examining cash conversion alongside earnings can therefore provide additional context about a company’s financial position.
To measure the relationship between accounting earnings and cash generation more precisely, investors can use the free cash flow conversion ratio. Our Apple FY2024–FY2025 analysis shows how reported net income can increase while free cash flow declines, and why one-time tax items can complicate the comparison.
Long-term investors also need to understand whether revenue growth is translating into sustainable cash generation. Free cash flow can support dividends, share repurchases, debt reduction, acquisitions, and reinvestment in the business, although management must decide how that cash is ultimately allocated.
Net income and free cash flow answer different questions. Net income measures accounting profitability under accrual rules, while cash-flow analysis helps investors understand how reported business activity translates into actual cash generation.
Accrual Accounting vs Cash Realities: Deconstructing the Financial Statements
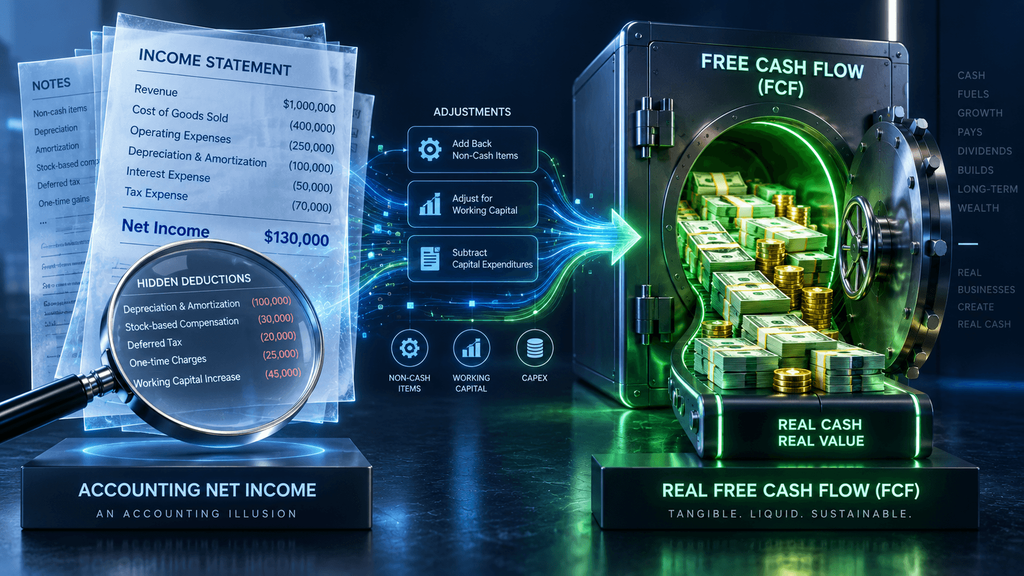
The difference between reported accounting net income and cash generation originates partly from accrual accounting. Under accrual accounting, revenue and expenses are generally recognized when the applicable accounting criteria are satisfied rather than simply when cash is received or paid. The statement of cash flows then helps investors see how operating activity, investing activity, and financing activity affected cash during the reporting period.
Capital expenditure accounting creates another important difference. When a company constructs production facilities or purchases long-lived equipment, those expenditures are generally capitalized on the balance sheet and recognized as depreciation or amortization expense over time when applicable. The cash flow statement, however, records the cash spent on capital expenditures in the period in which the payment occurs. A common FCF calculation then subtracts capital expenditures from operating cash flow.
| Evaluation Metric | Reported Net Income (GAAP) | Free Cash Flow (FCF) |
|---|---|---|
| Accounting Basis | Accrual-based accounting under applicable GAAP recognition rules | Commonly derived from cash-flow statement data |
| Common Calculation | Revenue and recognized gains less expenses and recognized losses, including applicable taxes | Cash Flow from Operations (CFO) − Capital Expenditures (CapEx) |
| CapEx Treatment | Qualifying expenditures are generally capitalized, with related depreciation or amortization recognized over applicable periods | Capital expenditures reduce cash flow in the period paid under the common CFO-minus-CapEx approach |
| Accounting Estimates | Can be affected by estimates and accounting judgments | Based on cash-flow statement amounts, although classification, working capital, and the definition of FCF still require analysis |
| Investor Use | Evaluating accounting profitability and earnings-based valuation | Evaluating cash generation, reinvestment needs, dividend coverage, debt capacity, and cash-flow-based valuation |
Once you have calculated free cash flow, the next step is to compare it with revenue. Our free cash flow margin guide explains how to calculate FCF margin and use it to evaluate how effectively a company converts sales into cash after capital expenditures.
Locating FCF on Yahoo Finance and Financial Terminals
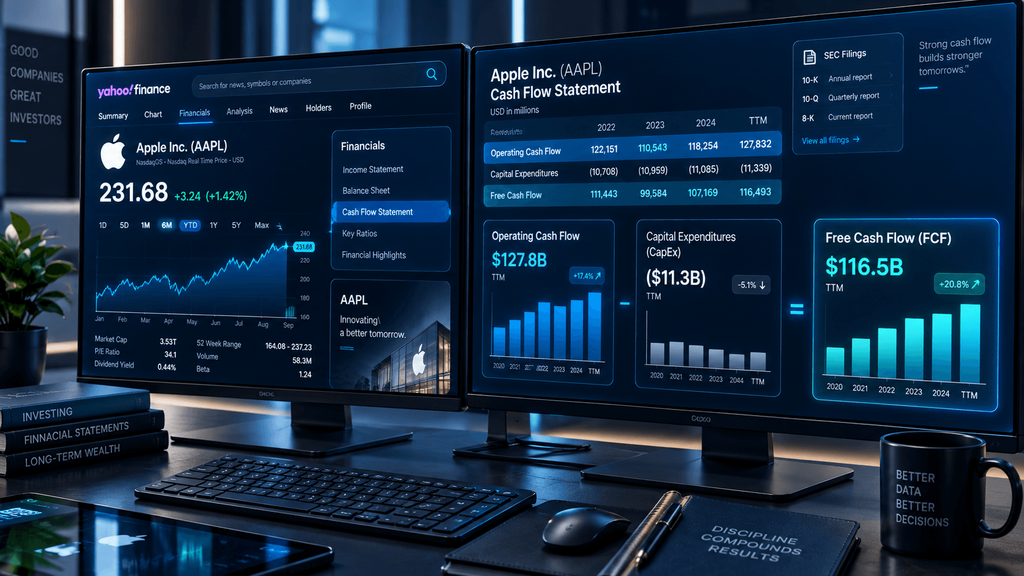
Individual investors can access the financial statement data needed to calculate free cash flow without professional market-data terminals. On public financial portals such as Investing.com and Yahoo Finance, investors can search for a company and review its cash flow statement. Depending on the provider, operating cash flow, capital expenditures, and a calculated free cash flow figure may be displayed.
A useful Free Cash Flow Guide should go beyond a single trailing twelve-month figure. Fast-growing technology companies and capital-intensive manufacturers can make large investments that temporarily reduce free cash flow. Conversely, a sustained decline in operating cash flow combined with rising receivables may warrant closer investigation into working capital and the underlying business.
Corporate disclosures provide additional context for working-capital movements, capital expenditures, stock-based compensation, acquisitions, and other items affecting cash flow. Investors can review annual and quarterly filings through the U.S. Securities and Exchange Commission (SEC EDGAR) database. Reviewing the underlying filing can also help explain why a company’s reported or adjusted free cash flow differs from a simple operating-cash-flow-minus-CapEx calculation.
Using Free Cash Flow for Valuation and Dividend Analysis
Free cash flow yield can complement earnings-based valuation multiples when investors evaluate a company’s valuation. A higher FCF yield may indicate that the market price is lower relative to the cash flow being generated, but the figure should not be interpreted in isolation. Growth expectations, business risk, capital requirements, debt, cyclicality, and the sustainability of current cash flow can all affect what valuation is reasonable.
Dividend analysis can also benefit from comparing cash dividends with free cash flow. The resulting FCF payout ratio or coverage ratio provides another perspective on how much of current free cash flow is being used for dividends. There is no universal payout threshold that guarantees dividend safety, however; capital requirements, debt obligations, cyclicality, liquidity, and management’s capital-allocation priorities also matter. For a practical case study examining cash-backed dividends and allocation considerations, review our comprehensive analysis on McDonald’s target price and disciplined tranche accumulation strategy.
A recent example is our AbbVie Q2 2026 earnings analysis, where first-half simple free cash flow of approximately $6.678 billion is compared with $6.156 billion of cash dividends. The resulting 92.2% FCF payout ratio and 1.08× coverage illustrate why a single six-month ratio needs to be interpreted alongside working capital, acquisitions, debt service and other cash demands.
Valuation therefore requires more than establishing a single target price from current free cash flow. Investors can examine how consistently a business converts revenue into cash, how much reinvestment it requires, and whether current cash generation appears sustainable across different operating conditions.
Frequently Asked Questions
Does negative free cash flow indicate an imminent corporate insolvency?
No. Negative free cash flow does not automatically indicate insolvency. A company may report negative FCF because it is making substantial capital investments for future growth. The interpretation becomes more concerning when weak cash generation persists and is accompanied by deteriorating revenue, liquidity pressure, rising debt obligations, or other signs of financial stress.
How do analysts differentiate maintenance CapEx from expansion CapEx?
Financial statements do not always provide a clean separation between maintenance and growth capital expenditures. Analysts may use depreciation, management disclosures, historical spending patterns, capacity additions, and project-level information as reference points, but depreciation should not be treated as a precise measure of maintenance CapEx. The distinction often requires judgment and additional company-specific disclosure.
How does stock-based compensation affect free cash flow figures?
Stock-based compensation is generally a non-cash expense that reduces GAAP earnings and is added back when reconciling net income to operating cash flow under the indirect method. As a result, conventional free cash flow can remain higher than a measure that treats equity compensation as an economic cost. Investors may therefore evaluate both reported cash generation and the dilution or economic cost associated with stock-based compensation.
Investment Disclaimer and Regulatory Notice
This publication is prepared exclusively for informational and educational purposes based on publicly accessible corporate filings and financial reporting data. Nothing herein constitutes individualized investment advice or a solicitation to buy or sell securities. All investment decisions involve risk, and investors maintain sole responsibility for their portfolio capital allocations.